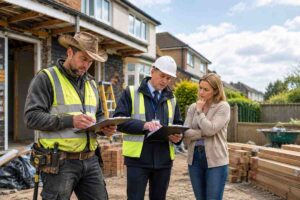

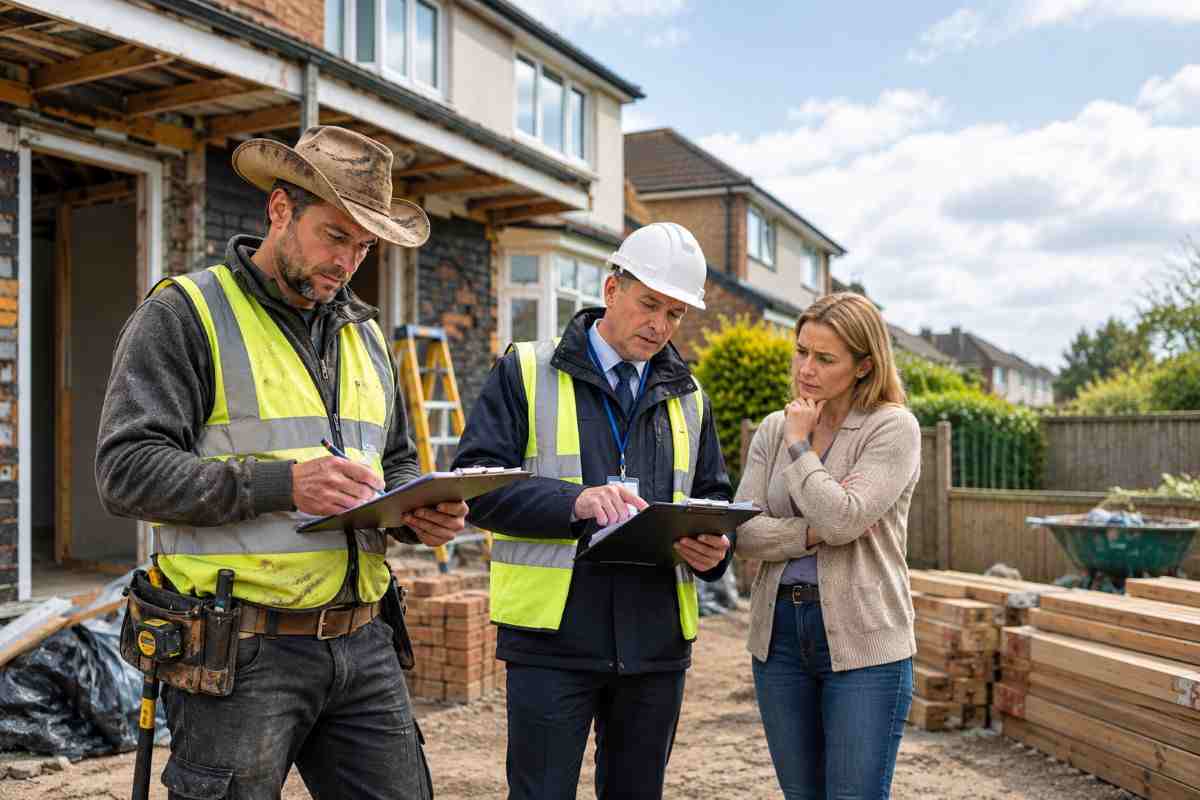
For anyone planning an extension, renovation or major home repair, the biggest worry is often not the work itself but what happens after the money changes hands. A new government-backed crackdown on so-called cowboy builders is now being rolled out, with measures designed to make it harder for homeowners to lose money when building work goes wrong.
But there is an important catch: despite the headlines, this is not a new compulsory licensing system for every builder. Instead, the government is backing two schemes intended to give consumers more information and greater control over payments.
What is actually changing?
The government announced the measures in August as part of a wider consumer-protection programme. The package centres on an Approved Code for the home improvement sector and Trusted Payments, a system designed to link payments to agreed stages of a project.
Trusted Payments is intended to give homeowners an alternative to simply handing over a large amount of money at the beginning of a job. Payments can instead be connected to agreed project milestones, so money is released as work progresses.
That matters because one of the most difficult situations for homeowners is paying a substantial amount upfront only for a project to be delayed, abandoned or completed poorly.
The Approved Code tackles a different part of the problem. It is designed to give participating businesses a recognised way to demonstrate higher standards around customer service, transparency and dispute resolution. The Furniture & Home Improvement Ombudsman says the first businesses are expected to join by the end of September, with the scheme fully operational by December 2026.
Does this mean builders now need a government licence?
No — and this is one of the biggest misconceptions surrounding the announcement.
The crackdown does not introduce compulsory licensing for all domestic builders. Nor does it mean that every builder in the UK must immediately join the new Approved Code or use Trusted Payments.
Both initiatives are intended to be voluntary. The government’s announcement is therefore better understood as an attempt to improve consumer protection and make reputable traders easier to identify, rather than as a new legal barrier preventing someone from trading as a builder.
That distinction matters when choosing a contractor. A builder not using the schemes is not automatically a cowboy builder, just as joining a scheme should not mean you can stop carrying out your own checks.
How could the changes protect your money?
The most direct benefit is the move towards milestone-based payments.
Instead of paying everything before work is completed, the project can be divided into agreed stages. The homeowner’s money is then handled through the payment system and released according to the agreed arrangements.
The second layer is greater transparency around the trader. The Approved Code is intended to make it easier for consumers to identify businesses that have committed to standards covering areas such as customer service and dispute resolution.
For homeowners, the related question is therefore not simply “Is my builder approved?” It is “What protection do I have if the project goes wrong?”
That should remain the starting point before signing a contract.
Common mistakes homeowners should avoid
One mistake is assuming that a government-backed scheme means the government guarantees the quality of every job. It does not.
Another is treating a trader’s membership of a scheme as a substitute for a written contract. Before work begins, homeowners should have clear written details covering the scope of work, total price or pricing method, payment stages, materials, timescales and what happens if the specification changes.
It is also risky to make large upfront payments simply because a builder says they need the money urgently for materials. A legitimate project may require some advance payment, but the amount and purpose should be clearly explained and documented.
What should you do before hiring a builder?
Start by getting written quotes and checking exactly what each one includes. Ask for references or evidence of comparable completed work and verify the trader’s business details independently.
For larger projects, make sure the contract explains how variations, delays, defects and disputes will be handled. If a builder offers Trusted Payments or belongs to an applicable approved scheme, check the scheme’s current terms rather than relying solely on a badge or logo.
And don’t rush because a trader says an offer is available “today”. A pressure tactic is a reason to slow down, not hand over money.
The bottom line
The cowboy-builder crackdown gives homeowners new tools rather than a blanket guarantee. Trusted Payments is intended to reduce the risk associated with handing over money before work is completed, while the Approved Code aims to make reputable home-improvement businesses easier to identify.
The schemes are being introduced in stages, so consumers should check the latest official terms and participating businesses before relying on them.
For anyone planning expensive work, the safest approach remains simple: check the trader, get everything in writing, understand the payment schedule and avoid paying more upfront than the project requires.